
Putting Bitcoin, cryptocurrency, and other digital assets inside a retirement account can open new possibilities, but the setup matters just as much as the assets themselves.
iTrustCapital brings self-directed retirement accounts, institutional custody, precious metals, and staking under one platform, making it an interesting option for anyone considering moving retirement funds beyond traditional markets.
In this iTrustCapital review, I’ll break down what the platform offers, where it stands out, and the tradeoffs worth knowing before you sign up.
>> Join iTrustCapital And Start Today <<
 What Is iTrustCapital?
iTrustCapital is a software platform for people who want to hold cryptocurrency, precious metals, and other supported assets in self-directed accounts without having to piece together custody and transactions on their own.
Its main focus is the Crypto IRA, with Traditional, Roth, and SEP IRA options available alongside Premium Custody Accounts and Treasury Accounts.
What makes the platform interesting is the way it brings several features under one roof.
Members can buy and sell digital assets around the clock, set up recurring purchases, use conditional transactions, stake eligible cryptocurrencies, and gain exposure to physical metals.
The bigger idea here is giving retirement savers direct access to alternative assets while keeping custody in institutional hands.
The company holds IRA assets through Fortis Bank as Qualified Custodian, while digital assets use providers such as Coinbase Custody, Fidelity Digital Assets, and Fireblocks.
At the end of the day, iTrustCapital all about making alternative assets feel much more manageable inside a self-directed account.
>> Open Your iTrustCapital Account Now <<
 How Does iTrustCapital Work?
Getting started begins with creating an account, verifying your email, setting up two-factor authentication, and completing the required identity checks.
After that, you choose the account type you want and select a funding method.
Once that’s taken care of, you’re able to run everything through the platform’s main dashboard.
This is where you can buy and sell supported cryptocurrency, set up recurring purchases, place conditional transactions, stake eligible assets, and manage the rest of your account activity.
Crypto transactions are available 24/7, a nice fit for a market that never really closes.
I also like that the platform keeps the actual decision-making in your hands.
iTrustCapital does not provide financial advice or tell you what to buy. Instead, it gives you the infrastructure to manage your own funds and assets.
There are a few minor nuances when moving from one asset to another, but the overall setup is simple enough that you do not need to be a crypto expert just to navigate the account.
>> Start Crypto IRA Investing With iTrustCapital <<
 What Types of Accounts Does iTrustCapital Offer?
iTrustCapital goes beyond a single Bitcoin IRA.
Traditional IRA
A Traditional IRA gives eligible account holders a retirement structure where taxes are generally deferred until qualifying withdrawals occur.
Instead of limiting the account to conventional means, iTrustCapital makes supported digital assets and precious metals accessible within the account.
Roth IRA
The Roth option is one of the platform’s biggest draws for me.
Roth IRAs use after-tax contributions, while qualified withdrawals can potentially be tax-free under applicable IRS rules.
That structure becomes even more appealing when looking at assets like Bitcoin that could appreciate substantially over a long retirement horizon.
SEP IRA
iTrustCapital also supports SEP IRAs, designed primarily for eligible self-employed individuals and small-business owners.
The current 2026 SEP contribution maximum is up to $72,000, subject to applicable income and IRS rules.
>> Explore iTrustCapital’s Crypto IRA Today <<
Premium Custody Account
While not a specifically for retirement, Premium Custody Accounts are also an option within the platform.
It’s possible to fund these through ACH, bank wire, and supported crypto deposits, opening up a wealth of opportunities for future growth.
This account makes more sense for someone who wants iTrustCapital’s custody infrastructure without putting the assets into an IRA.
Treasury Accounts
Treasury Accounts extend the platform to eligible organizations such as businesses, trusts, and nonprofits.
These accounts also provide access to supported digital assets while using the platform’s custody setup.
>> Buy Bitcoin With iTrustCapital Today <<
What Can You Buy With iTrustCapital?
 Cryptocurrencies
Crypto remains the centerpiece of iTrustCapital and was the asset that started it all.
The platform supports Bitcoin and a selection of other digital assets, stablecoins, and eligible staking tokens.
Supported cryptocurrencies can change from time to time, but there’s always a healthy amount to choose from.
 Physical Precious Metals
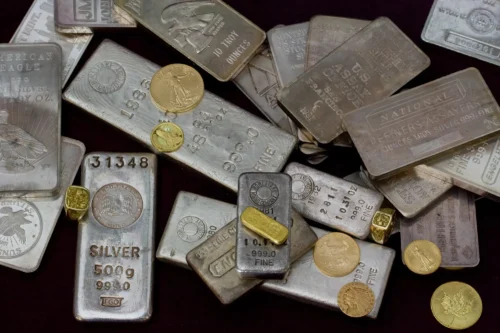
iTrustCapital also supports physical gold, silver, and platinum.
The metals are sourced through Kitco and stored at the Royal Canadian Mint. Ownership is recorded through DirectReserve, and clients own their respective ounces on a 1:1 basis.
What’s interesting is that there’s currently no separate storage fee while those metals remain on the platform.
That combination creates the ideal setup for someone who wants both digital and traditional hard assets inside the same broader retirement strategy.
>> Build Your Crypto IRA With iTrustCapital <<
 Is iTrustCapital Safe?
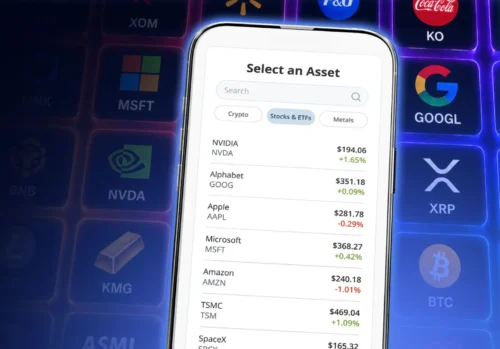
Security was one of the biggest things I wanted to investigate.
After all, a slick dashboard means very little if you’re uncomfortable with where retirement assets actually sit.
Institutional Custody
Fortis Bank serves as the Qualified Custodian for IRA accounts, which has been around since 1990. The site says they do not lend against crypto assets.
The digital-asset infrastructure here uses institutional storage providers that include:
- Coinbase Custody
- Fidelity Digital Assets
- Fireblocks
Those are established names in institutional crypto infrastructure.
Cold Storage and MPC
The security framework goes beyond a password protecting your account.
iTrustCapital puts the following security measures in place:
- Offline cold storage
- Multi-Party Computation (MPC)
- Two-factor authentication
- SOC 2 Type II-certified providers
- External security and financial audits
- Commercial crime insurance maintained by storage providers
I also like its closed-loop custody approach.
The platform does not use regular hot wallets for client accounts. That structure is designed to prevent someone who compromises login credentials from immediately draining IRA crypto to an outside wallet.
>> Access iTrustCapital’s Digital Asset Platform <<
Assets Held 1:1
The platform holds client assets for the benefit of account holders on a 1:1 basis and off iTrustCapital’s operating balance sheet.
I’m told they’re not mixed with money used for company operations.
That’s a meaningful distinction in crypto, where counterparty risk has burned plenty of people before.
Still, none of these protections make cryptocurrency itself risk-free.
Digital assets remain volatile, and commercial crime insurance should not be confused with a guarantee against every possible loss.
Is iTrustCapital Legit?
Yes, iTrustCapital checks the boxes I would want to see from a legitimate Crypto IRA platform.
The strongest evidence comes from the they handle your assets.
Fortis Bank acts as the Qualified Custodian for IRA accounts, while digital assets are stored through the institutional providers I mentioned earlier.
The 1:1 physical asset storage is another big feather in the company’s cap, since they’re not mixed with company operating funds or made available to satisfy the company’s own obligations.
A multitude of security measures reinforce my legitimacy findings and paint iTrustCapital in a very positive light.
On top of all that, its leadership team has nearly a century of experience between them, showing that this isn’t some fly-by-night adventure.
>> Move Retirement Funds To iTrustCapital <<
How Do You Fund an iTrustCapital IRA?
Funding an iTrustCapital IRA is fairly flexible, and there are three main ways to do it.
You can:
- Transfer an existing IRA
- Roll over an eligible previous employer retirement plan
- Make a cash contribution
Once you select the IRA you want to fund, the process starts from the Add Funds section on the dashboard.
Cash contribution instructions appear there, while transfer and rollover instructions are sent after you initiate the request.
If you’re moving retirement money from another provider, the transfer and rollover options are probably most relevant.
iTrustCapital does not state a maximum for qualified rollovers, and the minimum to open an IRA is $1,000.
Additional transfers, rollovers, and contributions generally require at least $500.
Note that you cannot normally move Bitcoin or another cryptocurrency from a personal wallet or regular exchange into the IRA as a new contribution. New IRA contributions must be made in USD.
However, crypto already held inside another qualified Crypto IRA may be eligible for an in-kind transfer, which lets you move the asset without liquidating it first.
That gives people with an existing Crypto IRA a much cleaner path into iTrustCapital.
>> Explore Bitcoin IRA Options With iTrustCapital <<
iTrustCapital Staking
Staking adds another dimension to the platform. When conducting this review, Ethereum and Solana were the eligible assets.
You can stake these cryptos directly from the dashboard inside Traditional, Roth, and SEP Crypto IRAs as well as Premium Custody Accounts.
Rewards depend on the blockchain network, participation, validator performance, and other factors.
There are fees associated with staking, and while a big vague, you can expect upwards of 22% off the top of any rewards you earn.
Bonding and unbonding periods can also prevent immediate access to staked assets.
So while staking has appeal, I wouldn’t treat it like a savings account paying guaranteed interest.
 What I Like About iTrustCapital
After digging through the platform, a few features stand out.
24/7 crypto access is a major plus. Cryptocurrency doesn’t close at 4 p.m., so being able to act without waiting for regular business hours makes sense.
No recurring platform maintenance fee also caught my attention. Retirement-account costs can eat into returns over long periods, and avoiding another annual charge is valuable.
I also like the combination of Traditional, Roth, and SEP IRAs, which gives different types of users some flexibility.
Institutional custody is another big one.
I feel more comfortable seeing names like Fortis Bank, Coinbase Custody, Fidelity Digital Assets, and Fireblocks involved than an unknown company controlling everything under one roof.
Finally, support for crypto, precious metals, recurring buys, conditional transactions, and staking makes iTrustCapital considerably more versatile than a basic Bitcoin-only retirement account.
>> Start Your iTrustCapital Roth IRA <<
Where iTrustCapital Could Be Better
No platform checks every box, and my biggest concern here is the 1% crypto transaction fee.
That’s reasonable enough for someone making occasional long-term purchases, but frequent buying and selling can make the costs stack up.
The lack of direct crypto-to-crypto pairs adds another wrinkle.
Moving between two assets may require two separate transactions, which can result in two fees.
IRA users also can’t simply move their crypto into a personal wallet while keeping those assets inside the same IRA custody arrangement.
That’s less an iTrustCapital flaw than a consequence of how the retirement structure works, but crypto purists who live by “not your keys, not your coins” should know what they’re signing up for.
iTrustCapital Pros and Cons
After reviewing iTrustCapital closely, these are the biggest strengths and a few limitations that stood out most.
Pros
- 24/7 cryptocurrency buying and selling
- Traditional, Roth, and SEP IRA support
- Institutional custody for digital assets
- Physical gold, silver, and platinum access
- No monthly platform maintenance fee
- Recurring purchases for long-term accumulation
- Eligible crypto staking inside supported accounts
- In-kind transfers from other Crypto IRAs
Cons
- 1% fee on crypto transactions
- No direct crypto-to-crypto trading pairs
- IRA assets remain under qualified custody
 Refund Policy
iTrustCapital does not offer a conventional money-back guarantee or refund policy.
That makes sense since this is an investment and custody platform rather than a subscription service.
Instead, account holders access or move funds through withdrawals, IRA distributions, or transfers, subject to applicable procedures, fees, and tax rules.
For IRA distributions, ACH withdrawals currently carry no fee, while bank-wire distributions cost $15.
>> Explore iTrustCapital’s Institutional Custody Setup <<
iTrustCapital Track Record and Past Performance
iTrustCapital does not publish a model portfolio or claim a verified investment-performance record, since clients choose and manage their own assets.
Because of that, I view past performance on how well the platform has supported itself and grown over the years.
To that point, it’s evolved beyond just Crypto IRA access, supporting Traditional, Roth, and SEP IRAs, Premium Custody Accounts, Treasury Accounts, staking, precious metals, and more than 90 digital assets.
It also uses Fortis Bank as Qualified Custodian for IRA accounts, while digital-asset storage involves institutional providers such as Coinbase Custody, Fidelity Digital Assets, and Fireblocks.
For me, that steady expansion and institutional infrastructure carry more weight than cherry-picked return figures that the platform itself does not promise.
>> Start Building With iTrustCapital Today <<
How Much Does iTrustCapital Cost?
iTrustCapital does not use tiered subscription plans or charge monthly or annual maintenance fees.
Instead, costs depend on account activity.
Crypto purchases and sales currently carry a 1% transaction fee, while precious metals have their own transaction pricing but no storage fee while held on the platform.
Treasury Accounts are also free to open with no startup or monthly charge.
There is no current sitewide promotional discount, so the main value comes from avoiding recurring platform fees.
A $75 fee also applies to Roth conversions when pre-tax IRA funds are converted into a Roth IRA.
Is iTrustCapital Worth It?
For me, iTrustCapital makes the most sense for individuals who want a simple way to combine Crypto IRA investing with long-term exposure to assets like Bitcoin, other supported cryptocurrencies, and precious metals.
The platform is not perfect. The 1% crypto fee can add up if you trade frequently, and IRA assets remain inside qualified custody rather than a personal wallet.
Still, iTrustCapital does a good job of making a complicated area feel much more approachable. You get 24/7 crypto access, multiple IRA options, staking, institutional custody, and no monthly platform fee.
Overall, this iTrustCapital review leaves me with a positive impression, especially for long-term users who value convenience and retirement-account structure over constant trading.


 Tags: